Buy televisiebeugelshop.be ?
We are moving the project
televisiebeugelshop.be .
Are you interested in purchasing the domain
televisiebeugelshop.be ?
domain@kv-gmbh.de · 0541-91531010
Buy televisiebeugelshop.be ?
What is a primary mortgage financing?
A primary mortgage financing refers to the initial loan that a borrower obtains from a lender to purchase a home or property. This type of financing is typically used to cover the majority of the purchase price of the property, and is secured by the property itself. The borrower makes regular payments to the lender over a set period of time, usually 15 or 30 years, until the loan is fully repaid. Primary mortgage financing is a common way for individuals to become homeowners without having to pay the full purchase price upfront. **
Where can I get a mortgage deed?
You can obtain a mortgage deed from a mortgage lender or financial institution that is providing you with the loan for purchasing a property. The mortgage deed is a legal document that outlines the terms and conditions of the mortgage agreement between the borrower and the lender. It is typically prepared by the lender's legal team and signed by both parties before the loan is disbursed. **


Similar search terms for Mortgage
Top-Angebote
Products related to Mortgage:
-
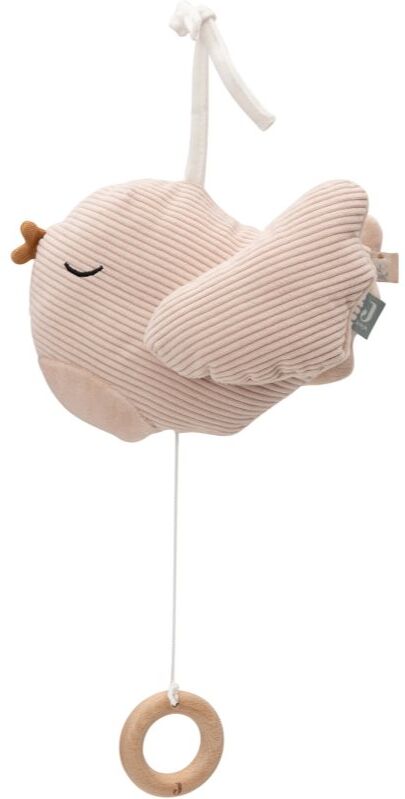
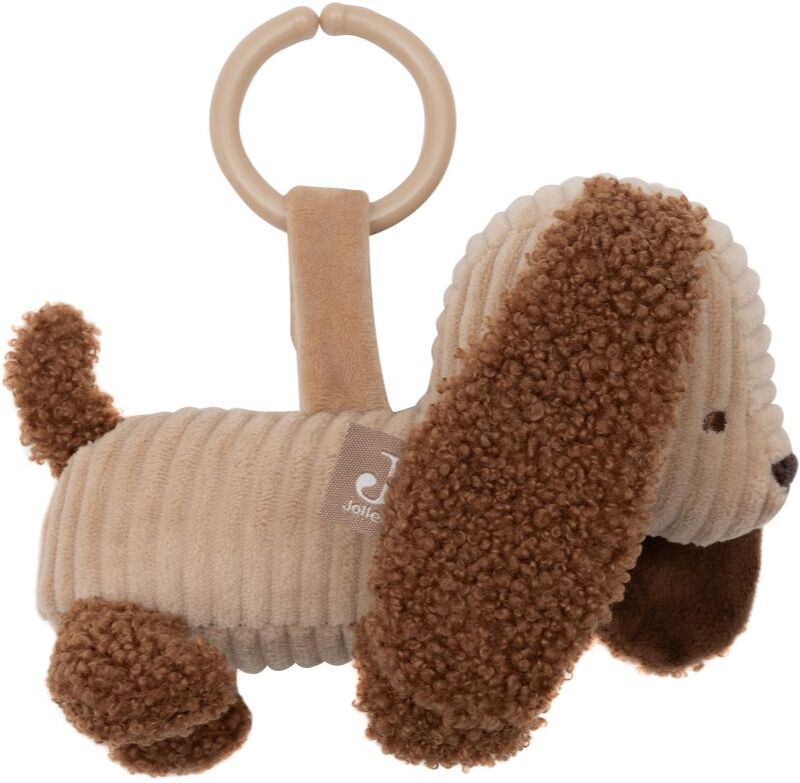
JOLLEIN Diego Musical Hanger jouet contrastant suspendu 0m+ 1 pcsJOLLEIN Diego Musical Hanger, 1 pcs, Jouets de suspension pour enfant, Quelques jours après la naissance, les bébés peuvent voir à une distance d’environ 25 cm et observent avec intérêt les objets en mouvement. Un jouet suspendu est donc le choix idéal pour les premiers mois de la vie de votre petit bout de chou. Parce qu’il est suspendu et qu’il présente un design et des couleurs ludiques, le jouet JOLLEIN Diego Musical Hanger éveille sa curiosité naturelle et capte toute son attention. En plus de le divertir, il l’aide également à développer son imagination, sa perception sensorielle, sa motricité et bien d’autres capacités. Le produit : le bruissement produit par les matériaux attire l’attention des enfants peut être placé sur une poussette, un siège auto ou un lit d'enfant développe la capacité du bébé à focaliser son attention stimule le développement de la vue et du toucher favorise le développement de la coordination main-œil léger et pratique, parfait pour partir en voyage design adorable, se présente sous la forme d’un animal peut être attaché presque partout grâce à sa pince pratique les différentes textures des matériaux stimulent le toucher de l'enfant Matériaux : en peluche Mode d’emploi : Attacher le jouet au bord de la poussette, hors de portée de l’enfant, et s’assurer qu’il est bien fixé.12,00 €*Shipping: 3,45 €Secure redirect to the provider
-
MenSteel Anneau en métal avec 1 boule Weight Hanger 90gFaites glisser lentement le Anneau en métal avec 1 boule Weight Hanger 90g autour de votre sexe. Sensation immédiate. Le métal froid réveille la peau, le poids attire doucement vers le bas. Chaque mouvement devient plus dense, plus présent, presque hypnotique.Poids et précision ⚙️Signé MenSteel,20,99 €*Shipping: 3,90 €Secure redirect to the provider
-
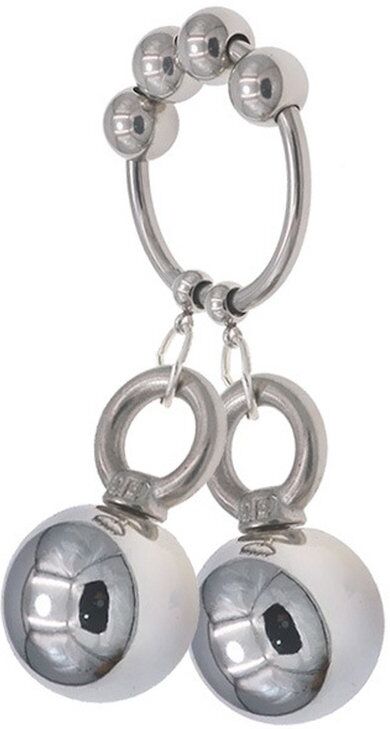
MenSteel Anneau en métal avec 2 boules Weight Hanger 160gFaites glisser doucement le Anneau en métal avec 2 boules Weight Hanger 160g autour du gland. Sensuel et précis. L’objet se fait sentir, lourd et froid, puis devient presque familier. Ce bijou viril attire le regard et intensifie les sensations, tout en affirmant votre goût pour les accessoires de22,99 €*Shipping: 3,90 €Secure redirect to the provider

-
How does the mortgage work in Monopoly?
In Monopoly, players can purchase properties when they land on them. If a player lands on an unowned property and chooses not to buy it, the property goes up for auction. If a player cannot afford to purchase a property, they have the option to mortgage their own properties to raise funds. When a property is mortgaged, the owner receives cash equal to half of the property's value, but they must pay 10% interest when they unmortgage the property. **
-
Can the mortgage on the house increase?
Yes, the mortgage on a house can increase under certain circumstances. For example, if the homeowner has an adjustable-rate mortgage, the interest rate can increase over time, causing the monthly mortgage payment to go up. Additionally, if the homeowner has a mortgage with an escrow account for property taxes and homeowners insurance, an increase in these expenses can also lead to an increase in the monthly mortgage payment. Finally, if the homeowner takes out a home equity loan or line of credit, this can also increase the overall debt secured by the house. **
-
What do I need to cancel a mortgage?
To cancel a mortgage, you typically need to pay off the remaining balance of the loan. This can be done by making a lump sum payment for the full amount owed. Once the loan is paid off, the lender will provide you with a satisfaction of mortgage document, which officially cancels the mortgage lien on the property. It's important to follow the specific procedures outlined by your lender to ensure the mortgage is properly canceled. **
-
How can I tell if a mortgage still exists?
To determine if a mortgage still exists on a property, you can start by checking the public records at the county recorder's office where the property is located. Look for the deed of trust or mortgage document that was originally recorded when the loan was taken out. You can also contact the lender directly to inquire about the status of the mortgage and any outstanding balance. Additionally, you can request a copy of your credit report, which should list any current mortgages or liens on your property. **


How was the house purchased without a mortgage deed?
The house was purchased without a mortgage deed through a cash transaction. This means that the buyer paid for the house in full with their own funds, rather than taking out a mortgage loan from a bank or other financial institution. This type of transaction is common in situations where the buyer has enough savings or access to funds to purchase the property outright, without the need for a mortgage. **
Should the mortgage be cancelled or transferred to another bank?
Whether the mortgage should be cancelled or transferred to another bank depends on various factors such as the terms of the current mortgage, the interest rates offered by other banks, and any penalties for cancelling the mortgage early. It is important to carefully evaluate these factors and consider the potential costs and benefits before making a decision. Consulting with a financial advisor or mortgage specialist can also help in making an informed decision. **
Top-Angebote
Products related to Mortgage:
-
SKECHERS Baskets Uno - Stand on AirDétails produit • Usage sportswear • Talon plat • Fermeture : A lacets • Semelle intérieure confortable Skechers Air-Cooled Memory Foam® • Semelle intermédiaire Skech-Air® à coussin d'air visible • Coupe compensée avec talon caché de 2,5 cm • Tige synthétique lisse perforée « Durabuck » • Semelle extérieure en caoutchouc souple et adhérente Composition et Entretien • Dessus/Tige : 97% polyuréthane, 3% polyester • Doublure : 100% polyester • Semelle intérieure : 100% polyester • Semelle extérieure : 100% caoutchouc Fiche produit relative aux qualités et caractéristiques environnementales • Origine de fabrication (piquage, montage, finition) : Vietnam Dernière mise à jour des informations : 02/04/202689,95 €*Shipping: 3,99 €Secure redirect to the provider
-
JOLLEIN Diego Musical Hanger jouet contrastant suspendu 0m+ 1 pcsJOLLEIN Diego Musical Hanger, 1 pcs, Jouets de suspension pour enfant, Quelques jours après la naissance, les bébés peuvent voir à une distance d’environ 25 cm et observent avec intérêt les objets en mouvement. Un jouet suspendu est donc le choix idéal pour les premiers mois de la vie de votre petit bout de chou. Parce qu’il est suspendu et qu’il présente un design et des couleurs ludiques, le jouet JOLLEIN Diego Musical Hanger éveille sa curiosité naturelle et capte toute son attention. En plus de le divertir, il l’aide également à développer son imagination, sa perception sensorielle, sa motricité et bien d’autres capacités. Le produit : le bruissement produit par les matériaux attire l’attention des enfants peut être placé sur une poussette, un siège auto ou un lit d'enfant développe la capacité du bébé à focaliser son attention stimule le développement de la vue et du toucher favorise le développement de la coordination main-œil léger et pratique, parfait pour partir en voyage design adorable, se présente sous la forme d’un animal peut être attaché presque partout grâce à sa pince pratique les différentes textures des matériaux stimulent le toucher de l'enfant Matériaux : en peluche Mode d’emploi : Attacher le jouet au bord de la poussette, hors de portée de l’enfant, et s’assurer qu’il est bien fixé.12,00 €*Shipping: 3,45 €Secure redirect to the provider
-
What is a primary mortgage financing?
A primary mortgage financing refers to the initial loan that a borrower obtains from a lender to purchase a home or property. This type of financing is typically used to cover the majority of the purchase price of the property, and is secured by the property itself. The borrower makes regular payments to the lender over a set period of time, usually 15 or 30 years, until the loan is fully repaid. Primary mortgage financing is a common way for individuals to become homeowners without having to pay the full purchase price upfront. **
-
Where can I get a mortgage deed?
You can obtain a mortgage deed from a mortgage lender or financial institution that is providing you with the loan for purchasing a property. The mortgage deed is a legal document that outlines the terms and conditions of the mortgage agreement between the borrower and the lender. It is typically prepared by the lender's legal team and signed by both parties before the loan is disbursed. **
-
How does the mortgage work in Monopoly?
In Monopoly, players can purchase properties when they land on them. If a player lands on an unowned property and chooses not to buy it, the property goes up for auction. If a player cannot afford to purchase a property, they have the option to mortgage their own properties to raise funds. When a property is mortgaged, the owner receives cash equal to half of the property's value, but they must pay 10% interest when they unmortgage the property. **
-
Can the mortgage on the house increase?
Yes, the mortgage on a house can increase under certain circumstances. For example, if the homeowner has an adjustable-rate mortgage, the interest rate can increase over time, causing the monthly mortgage payment to go up. Additionally, if the homeowner has a mortgage with an escrow account for property taxes and homeowners insurance, an increase in these expenses can also lead to an increase in the monthly mortgage payment. Finally, if the homeowner takes out a home equity loan or line of credit, this can also increase the overall debt secured by the house. **
Similar search terms for Mortgage
-
MenSteel Anneau en métal avec 1 boule Weight Hanger 90gFaites glisser lentement le Anneau en métal avec 1 boule Weight Hanger 90g autour de votre sexe. Sensation immédiate. Le métal froid réveille la peau, le poids attire doucement vers le bas. Chaque mouvement devient plus dense, plus présent, presque hypnotique.Poids et précision ⚙️Signé MenSteel,20,99 €*Shipping: 3,90 €Secure redirect to the provider
-
MenSteel Anneau en métal avec 2 boules Weight Hanger 160gFaites glisser doucement le Anneau en métal avec 2 boules Weight Hanger 160g autour du gland. Sensuel et précis. L’objet se fait sentir, lourd et froid, puis devient presque familier. Ce bijou viril attire le regard et intensifie les sensations, tout en affirmant votre goût pour les accessoires de22,99 €*Shipping: 3,90 €Secure redirect to the provider
-
MenSteel Ballstretcher avec Boules pendantes Steel Hanger Diamètre 34mm - Poids 390gLe métal capte la lumière et attire le regard. Ce Ballstretcher avec Boules pendantes Steel Hanger Diamètre 34mm - Poids 390g de MenSteel se distingue par sa conception solide et équilibrée. Il s’adresse à celles et ceux qui apprécient la précision, la sensation du poids et le contact froid de47,99 €*Shipping: 0,00 €Secure redirect to the provider
-
What do I need to cancel a mortgage?
To cancel a mortgage, you typically need to pay off the remaining balance of the loan. This can be done by making a lump sum payment for the full amount owed. Once the loan is paid off, the lender will provide you with a satisfaction of mortgage document, which officially cancels the mortgage lien on the property. It's important to follow the specific procedures outlined by your lender to ensure the mortgage is properly canceled. **
-
How can I tell if a mortgage still exists?
To determine if a mortgage still exists on a property, you can start by checking the public records at the county recorder's office where the property is located. Look for the deed of trust or mortgage document that was originally recorded when the loan was taken out. You can also contact the lender directly to inquire about the status of the mortgage and any outstanding balance. Additionally, you can request a copy of your credit report, which should list any current mortgages or liens on your property. **
-
How was the house purchased without a mortgage deed?
The house was purchased without a mortgage deed through a cash transaction. This means that the buyer paid for the house in full with their own funds, rather than taking out a mortgage loan from a bank or other financial institution. This type of transaction is common in situations where the buyer has enough savings or access to funds to purchase the property outright, without the need for a mortgage. **
-
Should the mortgage be cancelled or transferred to another bank?
Whether the mortgage should be cancelled or transferred to another bank depends on various factors such as the terms of the current mortgage, the interest rates offered by other banks, and any penalties for cancelling the mortgage early. It is important to carefully evaluate these factors and consider the potential costs and benefits before making a decision. Consulting with a financial advisor or mortgage specialist can also help in making an informed decision. **
* All prices are inclusive of VAT and, if applicable, plus shipping costs. The offer information is based on the details provided by the respective shop and is updated through automated processes. Real-time updates do not occur, so deviations can occur in individual cases. ** Note: Parts of this content were created by AI.